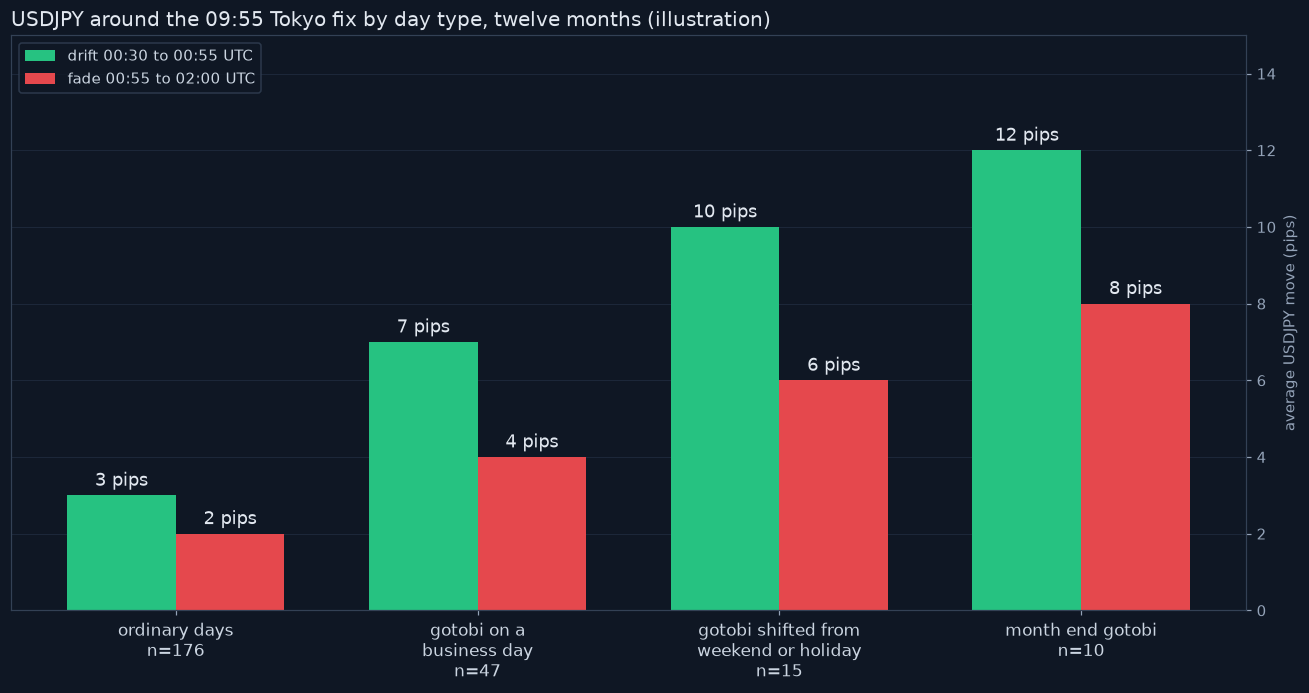
Using the same twelve months, I split gotobi days by whether the date itself was a business day. When a gotobi date lands on a weekend or a Japanese holiday, settlement usually moves to the business day before, and those shifted days behaved differently.
- img_13480_r2.png (57.58 KiB) Viewed 178 times
The chart shows the average drift from 00:30 to 00:55 UTC next to the fade from 00:55 to 02:00 for four groups. Ordinary days drifted 3 pips and faded 2, gotobi dates that fell on a business day drifted 7 and faded 4, shifted days drifted 10 and faded 6, and month end gotobi days drifted 12 and faded 8.
The shifted group is only 15 days and the month end group 10, so I read them as a hint. Still, the shifted days were exactly the ones I had been ignoring, because the calendar date did not look like a gotobi.
That also answers my own question from before, at least for this sample. The fade was roughly half to two thirds of the drift in every group, so it only pays when the drift was big enough to cover spread twice.
Do you keep your own list of Japanese holidays for this, or rely on the broker calendar? I found two dates my calendar had wrong.


