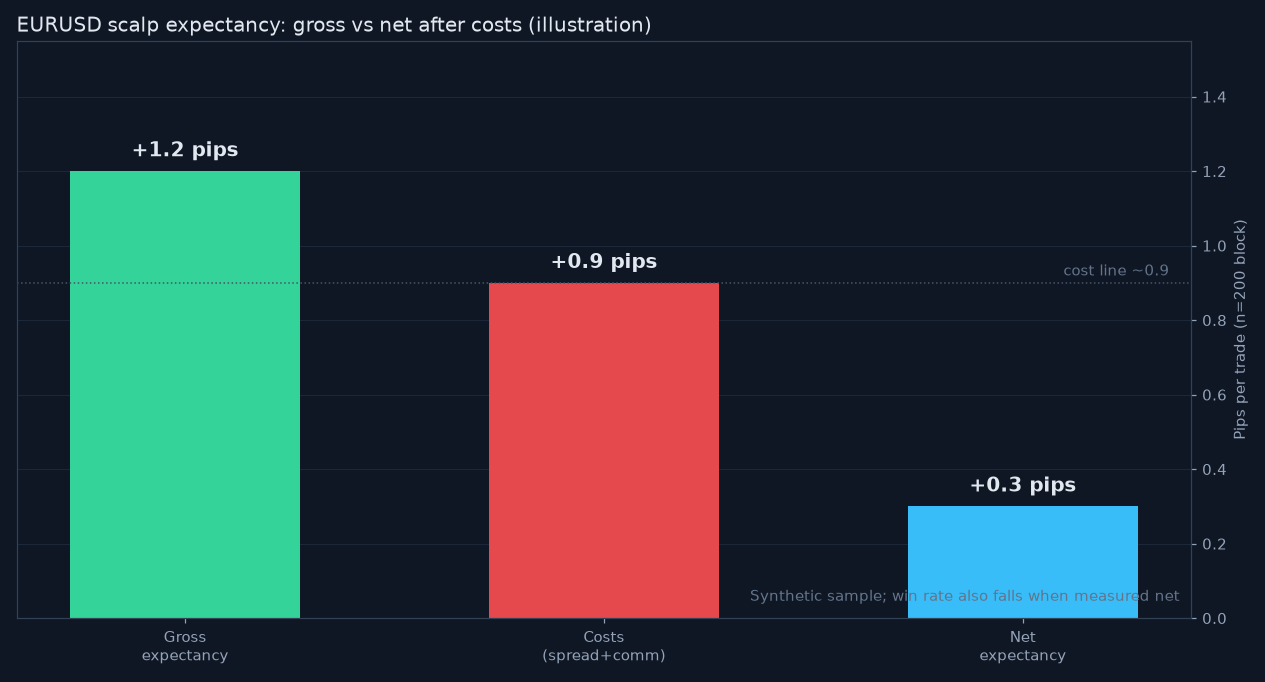
Fairman is right that costs change the win rate, not only the average. When I recompute my main EURUSD scalp on net fills, win rate drops about 4 points and average win shrinks, so the pretty +1.2 pip gross expectancy collapses to roughly +0.3 after spread and commission.
I measure on rolling blocks of 200 trades rather than a lifetime dump. That keeps a regime change visible instead of burying a bad quarter inside an old edge.
- img_13688_r1.png (51.1 KiB) Viewed 182 times
The illustration shows gross versus net expectancy on the same 200 trade block, with the cost line marked. Once costs sit near the gross edge, the strategy is basically a coin flip with fees.
Sample size still bites. With a per trade standard deviation around 8 pips, a few hundred trades leave a wide band around that +0.3, so I treat it as a go or no go filter rather than a precise forecast.
Do you publish expectancy to yourself in R or in pips? I switched to R last year so different pairs stay comparable after the pip value changes.



