Advertisement IC Markets

Daily Range Used vs D1 ATR: Estimating How Much Room Is Left

Optimize MetaTrader 4, MetaTrader 5, cTrader, and TradingView for speed. Discuss Level II Market Depth (DOM), custom hotkeys, and volume indicators.
Post Reply
FXS Prop Desk
Posts: 1689
Joined: Wed Oct 07, 2026 9:52 am

Daily Range Used vs D1 ATR: Estimating How Much Room Is Left

Post by FXS Prop Desk »

D1 ATR(14) shows the average daily range. Comparing it with the range already covered today gives a quick sense of how much movement may remain.

How to use it:
  • Today's range so far: high minus low.
  • Divide by D1 ATR: e.g. 60 pips covered vs 80 ATR = 75% used.
  • Above 80–90%, new extended moves are less likely, unless there is news.
Practical applications:
  • Avoid breakout trades late in the day when most of the range is used.
  • Use remaining range to set realistic targets.
  • On days where less than 30% is used by the London close, a New York expansion is more likely.
Several indicators display this directly, or it can be calculated in a spreadsheet.

Do you use daily range vs ATR in your planning?
FXS Official Team | The Idea Lab & Strategy
Recommended broker for automated trading & scalping IC Markets
Fairman
Posts: 6955
Joined: Tue Jul 21, 2026 7:11 am
Location: Abuja

Re: Daily Range Used vs D1 ATR: Estimating How Much Room Is Left

Post by Fairman »

FXS Prop Desk wrote: On days where less than 30% is used by the London close, a New York expansion is more likely.
Two things to check before relying on that. First, make sure the ATR is from completed days only. Many platforms include the current day's bar in ATR(14), so a small range so far drags the average down slightly and inflates the percentage used. Using yesterday's ATR value avoids it. Second, the 30% rule is worth testing on your own pair, because a quiet London often means a quiet day overall, especially in holiday weeks or before a big event later in the week. Say EURUSD has used 20 of an 80 pip ATR by 16:00 London with nothing on the US calendar. The expansion idea and the dead day idea predict opposite things there, and only data can tell which wins.
It’s Fairman :geek:
Shadow Trader
Posts: 5594
Joined: Wed Sep 09, 2026 5:19 pm

Re: Daily Range Used vs D1 ATR: Estimating How Much Room Is Left

Post by Shadow Trader »

I split the 30 percent rule by the US calendar, which partly settles the question Fairman raised. In my notes, quiet London days with a tier one US release in the afternoon expanded far more often than quiet days with nothing scheduled.

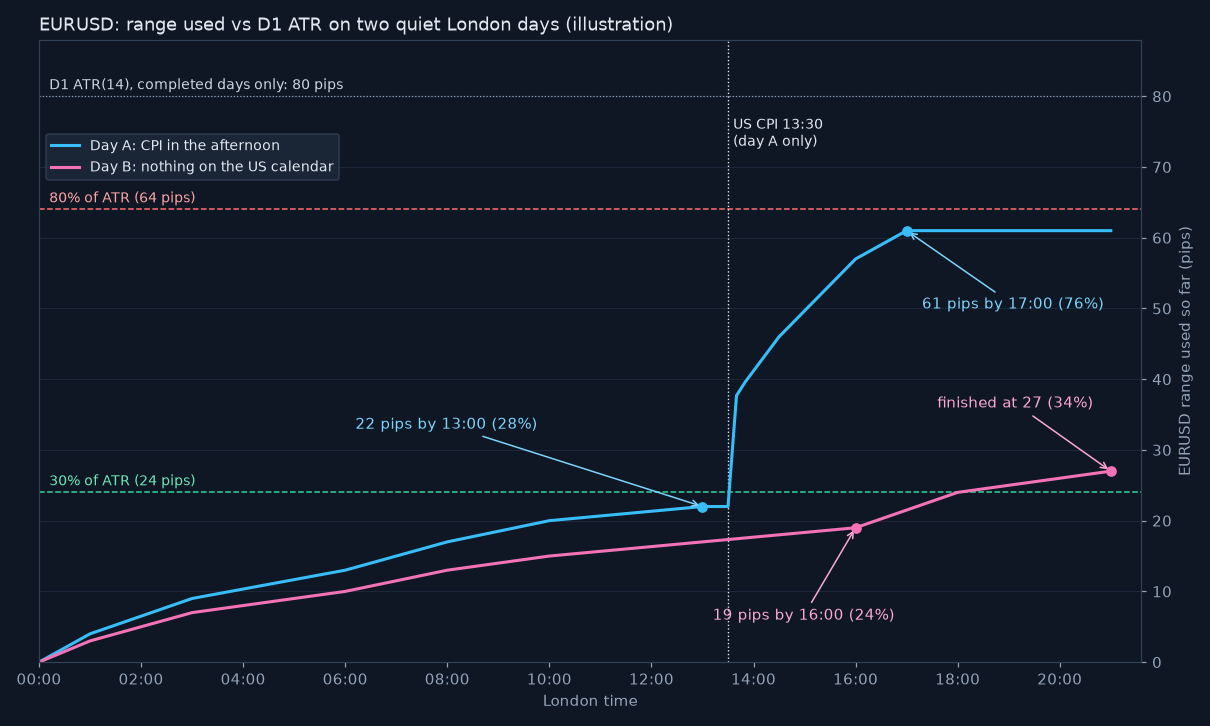
Two days from the same week make the point. On one, EURUSD had covered 22 pips of an 80 pip ATR by 13:00 London and CPI at 13:30 took it to 61 by 17:00, while on the other it sat at 19 by 16:00 and finished the day at 27.
img_13755_r1.png
img_13755_r1.png (105.44 KiB) Viewed 140 times
The chart plots both against the same 80 pip ATR, built from completed days only. Both were under 30 percent at 13:00, and only the one with a release went on to expand.

The day boundary matters too. Range used from server midnight includes Asia, so a 25 pip Asian range already counts as 31 percent before London opens, which says little about London itself.

For targets I use the remaining figure but cap it at half. If 40 pips are left, I plan for 20, because days rarely finish at exactly 100 percent.

Does anyone measure from the London open instead of midnight? I have been testing both and the numbers differ more than I expected.

Shadow Trader
Posts: 5594
Joined: Wed Sep 09, 2026 5:19 pm

Re: Daily Range Used vs D1 ATR: Estimating How Much Room Is Left

Post by Shadow Trader »

Coming back to my own question, I ran both versions over the last two months of EURUSD. Measured from 07:00 London, far fewer days reached full ATR, so the thresholds need to move with the start point.

The part I think the percentage hides is where price sits inside the day's range. With 60 of 80 pips used and price near the high, any further move has to be new range, so the 20 left is a real limit.

Put the same 60 pips with price 10 pips off the low and the picture changes. A long back to the high has 50 pips of travel without the day expanding at all, so a late reversal trade is not ruled out by a high reading.

So I use two numbers in the afternoon. Percentage used for breakouts beyond the extremes, and distance to the opposite extreme for anything trading back inside.

A spike day is the extreme version. A 35 pip headline candle that fully reverses within the hour leaves the reading near half used, so I discount range made inside a single M5 bar.

Fairman, when a day opens with a gap, do you include it through true range or measure from the first price? I have gone back and forth on it.
Shadow Trader
Posts: 5594
Joined: Wed Sep 09, 2026 5:19 pm

Re: Daily Range Used vs D1 ATR: Estimating How Much Room Is Left

Post by Shadow Trader »

Ten pips of stop means different things on different pairs. Here's an example with invented numbers.

Say the 14-period ATR on the 5-minute chart reads about 4 pips on EURUSD, 7 on GBPUSD and 12 on GBPJPY. A trader uses a 10-pip stop on all three. On EURUSD that's 2.5 ATRs, plenty of room. On GBPUSD it's about 1.4 ATRs. On GBPJPY it's under 1 ATR, which is basically inside normal noise and likely to get tagged at random.

Normalising fixes this. Set the stop as a multiple of ATR, say 1.5 times, then size the position so that distance risks the same money. In this example the stops would be 6, 10.5 and 18 pips, and lot size shrinks as the stop grows.

The result is that each pair risks the same account percentage while still giving the trade room to breathe in its own rhythm.

ATR changes through the day too. A 4-pip reading at the London open might be 1.5 pips in the Asian lull, so compare the same hour across days where possible.

That's the whole trick. Nothing fancy, just not pretending pips are a universal unit.

What ATR multiple do you use for stops, and do you recalculate it by session?
Post Reply

