Page 1 of 1
Rebuilding my prop-safe lot ladder for metals during CPI week
Posted: Tue Sep 22, 2026 3:02 pm
by LondonScalper
CPI week is when my prop-safe lot ladder for metals gets rebuilt, not when I invent courage.
Gold volatility rises, firm daily loss maths get less forgiving, and the lot size that felt fine last week becomes a process risk. I step the ladder down before the week starts: smaller base lot, slower scale-in, stricter invalidation.
Rebuild checklist
1. Recalculate max lot from daily loss and typical gold stop distance after costs.
2. Cap adds — metals impulsiveness loves pyramids that prop rules hate.
3. Pre-commit blackout around the CPI window itself.
Rebuilding is maintenance. Pretending last month’s ladder still fits is how funded accounts get surprised.
How do you adjust metals size on prop into CPI week — formula, or hard half-size habit?
After CPI week I do not automatically restore the old ladder on Monday. I need a quiet sample first. Volatility hangover is real in metals; nostalgia for last month size is not a risk model.
The rebuilt ladder is printed beside the screen for CPI week so I do not scale back up mid-impulse out of habit.
Re: Rebuilding my prop-safe lot ladder for metals during CPI week
Posted: Mon Oct 12, 2026 10:53 am
by Fairman
LondonScalper wrote: Recalculate max lot from daily loss and typical gold stop distance after costs.
A worked version of that first step, with made-up round numbers. Say the daily limit leaves room for 0.5% per trade on a 100k account, so $500. The typical gold stop is $3, and on CPI week you might expect around $0.50 of slip on a stop, so size off $3.50. On a contract of 100 ounces per lot, a $1 move is $100 per lot, so that stop costs $350 per lot and the max is about 1.4 lots. Fold commission per lot into the $3.50 and it comes down a little more. The step people skip is checking the contract size, because some brokers and prop servers quote gold at 1 or 10 ounces per lot, and copying a lot figure from one account to another can be out by a factor of ten. Redoing the sum each Sunday with that week's expected stop is basically the ladder.
Re: Rebuilding my prop-safe lot ladder for metals during CPI week
Posted: Tue Oct 13, 2026 2:46 am
by Shadow Trader
Fairman's sum is the one I run too, but on CPI week I don't size every day off the same stop. The $3 figure belongs to the quiet days, and on the release day I size off what the stop needs after the print, often closer to $5 with slip.
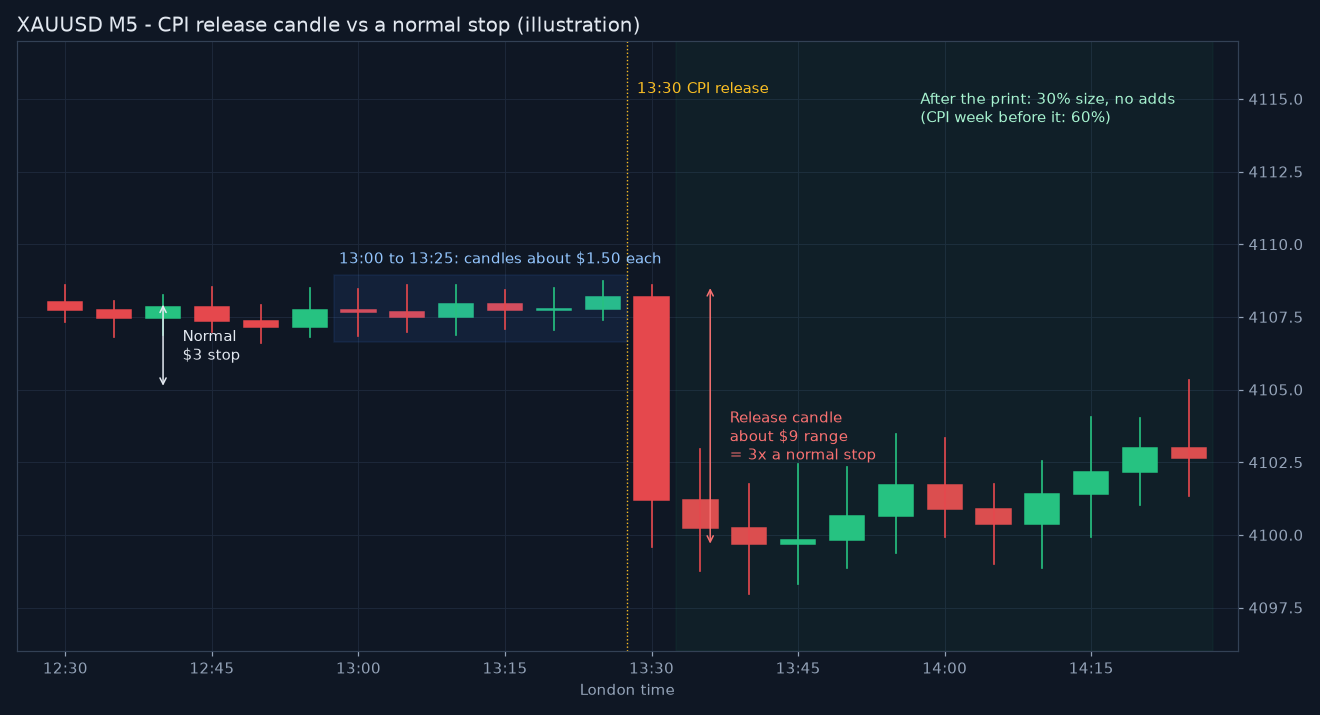
The attached chart is a made up XAUUSD M5 illustration of the release. Candles run about $1.50 through the half hour before 13:30, then one candle covers around $9, three times a normal stop.
- img_12627_r1.png (65.06 KiB) Viewed 383 times
So my ladder has three rungs rather than one number. Normal weeks run at full size, CPI week at 60% of it, and the release day after the print at 30% with no adds.
Adds are where the ladder usually breaks for me. I only add once the first stop sits at entry, and the combined open risk has to fit inside one rung, not one rung per position.
On restoring size, I give the quiet sample a number. Full size comes back once the average M5 range over a London morning is near its level from the week before CPI, usually two or three sessions.
The contract size warning matters with two prop accounts. Do you keep a ladder per server, or one in risk terms converted each time?
Re: Rebuilding my prop-safe lot ladder for metals during CPI week
Posted: Thu Oct 15, 2026 11:35 pm
by Shadow Trader
LondonScalper, the part of the ladder I see people forget is everything else in CPI week. PPI often lands a day either side, retail sales or claims can share the same 13:30 slot, and gold reacts to all of them through yields.
So my reduced rung covers the whole week, but the extra cut applies to each of those release mornings, not only to CPI day. In a typical week that is two or three mornings rather than one.
Pending orders are the other trap with a blackout. A buy stop left above the morning range can trigger on the print, so the blackout starts with cancelling pendings, not just closing open trades.
Fairman, on the other release mornings my stop exits in the first two minutes after 13:30 slipped closer to $1.20 than $0.50. Outside those two minutes it was near your figure, so I keep two slip numbers in the sum.
Plugged into your example, $3 plus $1.20 gives $420 per lot, and the $500 allows about 1.2 lots instead of 1.4. It looks small on paper, but it decides whether a second loss that day breaks the limit.
Do you size off the expected slip or the worst one you have logged? My worst on gold was over $4, which would make the ladder almost useless.
Re: Rebuilding my prop-safe lot ladder for metals during CPI week
Posted: Sat Oct 31, 2026 5:40 am
by Shadow Trader
Commission on a raw spread account is charged per lot, per side. A typical figure is 3.50 dollars per lot per side, so 7 dollars for the round turn. On a 0.01 lot trade, that's 0.07 dollars.
Brokers round commissions in different ways. Some round up to the nearest cent, others to the nearest tenth of a cent, and some apply a minimum per ticket. A minimum of 0.10 dollars per trade turns a 0.07 commission into 0.10, which is a 43 percent markup.
For scalpers using small sizes to test a system, the distortion can be large. A micro-lot strategy that looks profitable in gross terms becomes unprofitable once the minimum commission is applied. When scaling up, the effective cost per lot drops, and the results change.
A review of the statement for a handful of small trades shows what the broker really charges. Dividing the commission by the lot size gives the effective rate. If it's higher than the advertised one, rounding or a minimum applies.
This matters when forward-testing on a small account before going bigger. The cost structure at 0.01 lots isn't the same as at 1.0 lots, and results from one don't transfer cleanly to the other.
What commission rate came out of the effective calculation on small tickets?