Page 1 of 1
GBPUSD ORB after a compressed Asia range: my expansion filter
Posted: Wed Sep 16, 2026 10:04 pm
by LondonScalper
GBPUSD at London open behaves differently depending on what Asia left behind.
When Asia is a
compressed range, London often expands. That is when I allow an ORB. When Asia already travelled, London frequently mean-reverts or chops — ORB breakouts there have been expensive noise for me. Compression is not "quiet because I feel bored"; it is width versus recent sessions.
Rule I actually follow: measure Asia high–low before the London cash window. If that width sits in the lower third of the last twenty sessions, ORB is permitted (break plus retest). If Asia width is already large, I switch to pullback or stand-aside — I do not force the breakout costume. UK data into the open cancels the filter entirely; then the stand-aside window owns the morning.
I keep the same stop philosophy either way: other side of the box, no widening because cable "always runs".
- Do you quantify Asia compression before GBP ORB, or is it visual?
- What percentile / lookback do you trust?
Trying to keep this mechanical enough that Monday mood cannot override it.
Re: GBPUSD ORB after a compressed Asia range: my expansion filter
Posted: Sun Sep 27, 2026 4:58 pm
by PropScalpDesk
Lower third of twenty sessions is close to what I use. The adjustment I made is for Mondays. Monday's Asia session follows the weekend and can be unusually quiet or distorted by a gap, so it drags the percentile around. I compare Mondays only against earlier Mondays, and I measure Asia as a fixed window, 00:00 to 07:00 London, so that daylight saving changes don't quietly shift what counts as Asia.
Re: GBPUSD ORB after a compressed Asia range: my expansion filter
Posted: Fri Oct 16, 2026 8:59 pm
by Shadow Trader
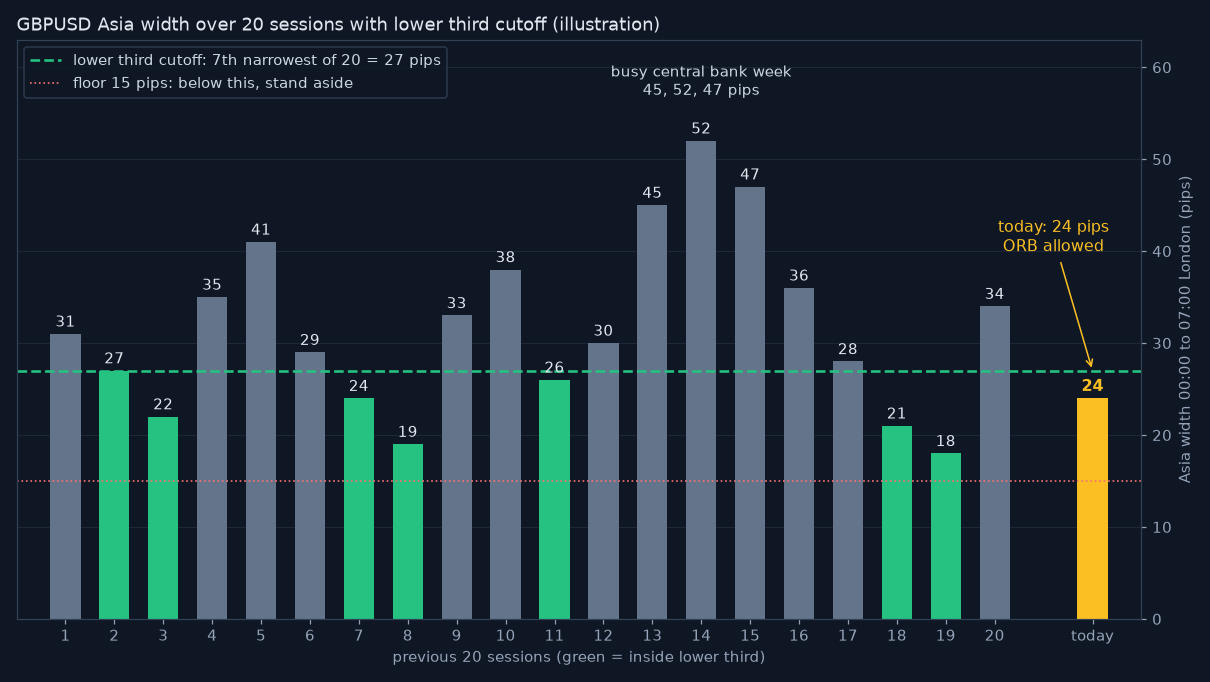
I quantify it, and my numbers land close to yours. For the 20 sessions before this one, GBPUSD Asia widths ran from 18 to 52 pips, measured on the same fixed 00:00 to 07:00 London window PropScalpDesk uses.
Lower third of 20 means the 7 narrowest, and the seventh came out at 27 pips. Today's Asia was 24 pips, so the ORB was allowed.
- img_12451_r1.png (71.72 KiB) Viewed 109 times
The chart lays out those 20 sessions with the 27 pip cutoff and today's bar on the right. Notice the three wide sessions in the middle of the window at 45, 52 and 47 pips, which is what a busy central bank week does to the lookback.
One gap in a pure rank rule is that it does not care how far below the line a session sits. Asia sessions under about 15 pips have mostly been holiday or pre data days for me, and London stayed flat on most of them instead of expanding.
So I added a floor at 15 pips. Below it the filter says stand aside, the same as when Asia was already wide.
Comparing Mondays only against earlier Mondays sounds right but needs a long lookback. Twenty Mondays is almost five months, so do you shorten the count for that day or accept the older sample?
Re: GBPUSD ORB after a compressed Asia range: my expansion filter
Posted: Sat Oct 17, 2026 10:28 pm
by Shadow Trader
A weakness in the rolling rank showed up in August. After three weeks of holiday trade the whole lookback was narrow, so the lower third cutoff fell to about 19 pips and the filter kept approving boxes that were only quiet by summer standards.
The fix I am testing divides Asia width by the 20 day average daily range instead of ranking it against other Asia sessions. A ratio under 0.25 counts as compressed, and that number stays meaningful when the whole market slows down or speeds up.
On most normal weeks the two methods agree. They split mainly after a big move, when the daily range is inflated and the ratio approves an Asia session the rank would have rejected.
The UK data rule needs a definition as well. Releases such as GDP and retail sales come out at 07:00 London, before the box even starts, so I treat a 07:00 print as a reason to skip rather than as something already out of the way.
My Monday question from last time is still open on my side. Until I have a better answer, Mondays are excluded from the filter and only get a pullback entry.
Re: GBPUSD ORB after a compressed Asia range: my expansion filter
Posted: Thu Oct 29, 2026 6:53 am
by Shadow Trader
Renko and range bars ignore time. A new bar forms only after price has moved a set number of pips. The result is a chart that looks clean, with less noise and clearer trends.
The appeal is obvious. Small wiggles disappear, and trends appear as smooth runs of bars in the same direction. Support and resistance seem easier to identify.
The costs are less visible. Because time is removed, there is no sense of how long a move took. Many platforms build these bars from closing prices, and some repaint when a bar reverses. The bars can also mask spread effects, which are critical on short timeframes.
Backtests on such charts can be misleading. A signal that triggers at the close of a Renko bar might not have been tradable at that price in reality, since the price could have gone through it quickly.
They can be a useful visual aid, but they should be treated as a filter for reading structure, not as a source of exact entry prices.
If a range bar chart is used for entries, comparing a few weeks of signals against actual fills on a time chart shows how far the real fill sits from the signal price. The gap is the real cost of the clean look.
Have you traded from Renko or range bars, and how did the execution compare with what the chart implied?