Page 7 of 27
Re: Exponencial money management
Posted: Thu Sep 17, 2026 10:47 pm
by Fairman
Using Multiple Take-Profit Levels Effectively
Beyond the simple two-stage partial-profit framework covered earlier in this series, some scalpers benefit from a more structured, multi-level take-profit approach — splitting a position across three or more predetermined exit points rather than just an initial partial and a final target.
Why More Than Two Levels Can Add Value
A single target forces an all-or-nothing bet on reaching one specific price. A two-level partial/final structure already improves on this, but still concentrates the remaining position's outcome entirely on whether the single final target gets reached. A multi-level structure — perhaps a quarter of the position at each of several successive liquidity levels — smooths this out further, capturing value incrementally as price progresses through several genuine, predetermined structural levels rather than depending heavily on any single one being reached.
A Practical Multi-Level Framework
Using the internal-versus-external liquidity distinction covered earlier in this series, a multi-level structure might close a portion at the first internal liquidity level encountered, another portion at a second, more significant internal level or a minor external level, and reserve a final portion for the most significant external liquidity target identified in the original analysis — with the stop moved to breakeven or better after the first level is reached, similar to the two-stage framework already covered.
Where This Adds Genuine Value Versus Unnecessary Complexity
For genuinely longer, more extended moves with several plausible, well-defined intermediate structural levels along the way, a multi-level approach can meaningfully smooth out the outcome distribution and reduce the "did I hold too long past the final target" or "did I sell my final portion too early" tension covered throughout this series' trade management discussion. For shorter, more compressed scalps with only one clear, nearby target and no meaningful intermediate structure, adding multiple artificial levels just to have more than one exit point adds complexity without adding genuine value — the additional levels need to correspond to real, identifiable structure, not be manufactured arbitrarily just to create more stages.
The Execution Cost Consideration
Each additional partial exit carries its own execution cost — spread paid again on each closed portion, and additional cognitive load managing more moving pieces during an already time-pressured scalping session. This tradeoff means multi-level exits are best reserved for setups genuinely large enough, in terms of overall targeted move and clearly identifiable intermediate structure, to justify the added complexity and cost — not applied uniformly to every single scalp regardless of its actual size and structure.
A Reasonable Default
For most typical scalping setups, the simpler two-stage partial/final framework already covered in this series captures most of the practical benefit with considerably less complexity. Reserve a fuller multi-level approach for the specific subset of setups — larger targeted moves, clear multiple intermediate structural levels — where the added structure genuinely corresponds to real, identifiable price levels rather than being imposed artificially onto a shorter, simpler trade.
The Underlying Point
More exit levels isn't automatically better — the value depends entirely on whether each additional level corresponds to genuine, identifiable structure worth respecting, following the same discipline this entire series has emphasized: plan levels in advance based on real analysis, don't manufacture arbitrary stages just for the sake of having more of them.
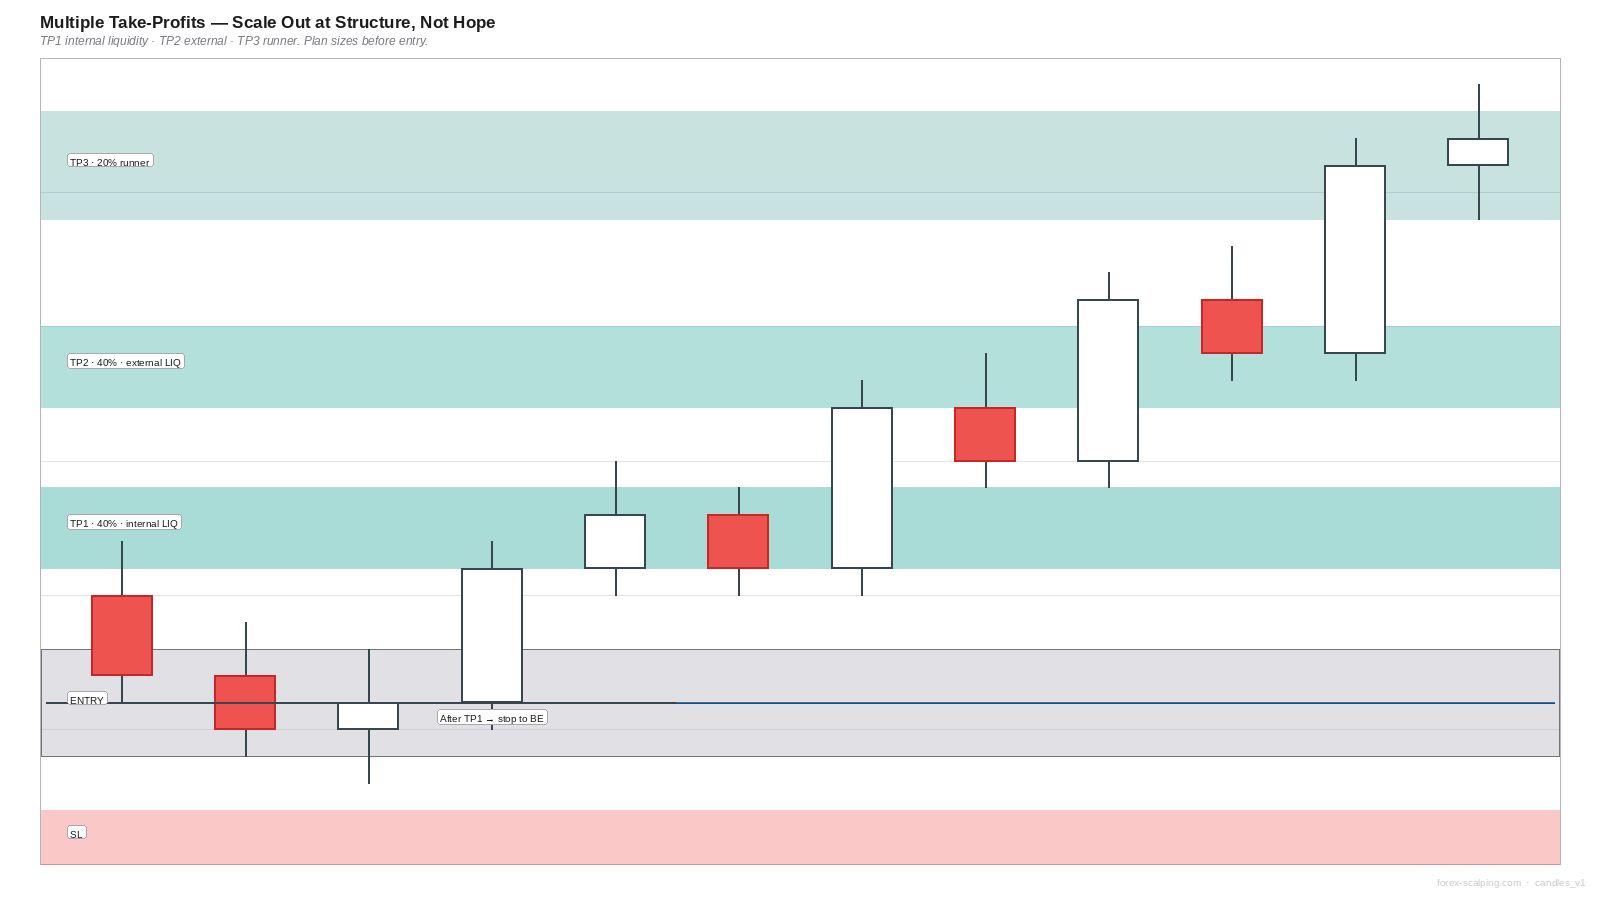
- diagram.png (26.1 KiB) Viewed 377 times
Re: Exponencial money management
Posted: Thu Sep 17, 2026 11:09 pm
by Fairman
Building a Trade Execution Checklist for Fast Markets
Beyond the pre-trade confluence checklist covered earlier in this series, fast-moving market conditions — news spikes, sharp liquidity sweeps, high-volatility sessions — call for a separate, execution-focused checklist specifically designed for the compressed decision windows these conditions create.
Why Fast Markets Need Their Own Checklist
The confluence checklist covered earlier in this series is designed for methodical, unhurried evaluation of a developing setup. Fast market conditions compress the available decision window dramatically, and attempting to run through the full, methodical checklist in these conditions can mean missing the actual entry window entirely — connecting directly to the earlier post on analysis paralysis, except here the constraint is genuinely external (the market moving faster than deliberation can keep pace with) rather than purely internal hesitation.
A Practical Fast-Market Execution Checklist
Is my position size pre-calculated for a range of likely stop distances, or do I need to calculate it live? Fast markets don't leave time for on-the-spot position sizing math — having pre-calculated size options ready for a few likely stop-distance scenarios (per the position sizing formulas post covered earlier) removes this specific bottleneck from the live decision.
Is my stop level based on a structural point I've already identified, or am I picking one reactively in the moment? The same discipline from the earlier posts on stop placement applies here with extra urgency — fast markets are exactly the conditions where a reactively-chosen, poorly-placed stop is most likely to get clipped by normal, elevated volatility.
Am I confident this specific fast move has genuine structural or liquidity significance, or am I reacting purely to speed and excitement? This is the fast-market equivalent of the confluence checklist's core question, compressed into a single, quick gut-check rather than a full methodical review — speed and excitement alone are not confluence, and this distinction matters more, not less, when things are moving quickly and the temptation to just "get in on the action" is strongest.
Do I have a clear, immediate plan for what invalidates this trade, without needing to think it through once I'm already in the position? In fast conditions, having this answer ready before entry, rather than working it out after, is what prevents the kind of frozen, reactive management that tends to produce exactly the sunk-cost and stop-moving patterns covered earlier in this series.
Why Pre-Building This Checklist Matters More Than Having It in the Moment
The value of this checklist comes almost entirely from having thought through and internalized it during calm conditions, well before a fast-moving situation actually arrives — trying to consciously work through a checklist for the first time while price is already spiking defeats the purpose. This is closely related to the one-page trading plan covered earlier in this series, but specifically adapted and rehearsed for the compressed, high-pressure conditions fast markets specifically create.
The Underlying Point
Fast markets don't excuse abandoning discipline — they require a specifically adapted, pre-rehearsed version of it that can be applied within a genuinely compressed decision window, rather than either freezing under the full methodical checklist's demands or abandoning structure entirely in favor of pure reactive excitement.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:32 pm
by Fairman
Funded Account Psychology: Trading Someone Else's Money
Moving from a personal account to a prop firm funded account, following the evaluation process covered earlier in this series, introduces a genuinely distinct psychological dynamic that deserves direct attention beyond the mechanical rules of the programs themselves.
Why Trading "Someone Else's" Capital Feels Different
Even when the actual trading process should theoretically be identical, there's a real, common shift in how losses and risk feel once the capital being risked isn't purely your own — some traders find this actually reduces pressure (the money doesn't represent their own life savings, which can paradoxically improve discipline by lowering personal financial anxiety), while others find it introduces a different kind of pressure (a sense of obligation or performance anxiety tied to not wanting to "lose" a funded opportunity they worked to earn).
The Specific Risk of Treating Funded Capital as Less "Real"
A trader who unconsciously treats funded capital as somehow less consequential than personal capital risks a subtle but genuine discipline erosion — taking marginally lower-quality setups or slightly oversized positions specifically because the psychological weight feels different, even though the actual consequences (losing funded status, having to requalify) are genuinely significant. This is worth watching for directly, since it doesn't always register consciously as reduced discipline in the moment.
The Opposite Risk: Excessive Caution From Performance Pressure
Conversely, some traders become overly cautious on a funded account specifically because of the pressure not to "waste" a hard-earned opportunity — hesitating on genuinely valid setups, cutting winners unusually early, or under-sizing positions well below what the account's actual risk parameters would reasonably support. This mirrors the hesitation patterns covered throughout the earlier psychology posts in this series, but with the funded-account-specific pressure as the particular trigger.
A Practical Approach to Maintaining Consistent Discipline
The most reliable approach is treating funded capital with the exact same rule-based discipline covered throughout this entire series — the same written plan, the same confluence checklist, the same position sizing formula — regardless of whether the capital is personal or funded. Deliberately noticing and naming which direction (excessive looseness or excessive caution) you personally tend toward with funded capital specifically is a useful, honest first step toward correcting for it.
Why This Matters for Long-Term Success in These Programs
Prop firms are, in a real sense, specifically testing for consistent discipline that doesn't shift based on whose capital is technically at risk — a trader whose behavior meaningfully changes once real capital is on the line, in either direction, is demonstrating exactly the kind of inconsistency these programs' drawdown rules are designed to catch and penalize.
The Underlying Point
Funded account trading introduces a genuine, distinct psychological layer beyond the mechanical program rules covered earlier in this series — recognizing your own specific tendency (loosening or tightening discipline under this particular pressure) and consciously correcting for it is as important to long-term success in these programs as the underlying strategy itself.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:34 pm
by Fairman
The Emotional Difference Between Demo and Funded Accounts
The gap between demo trading and live personal-account trading, covered earlier in this series, has a lesser-discussed counterpart: the gap between a funded prop firm account and a personal live account, which carries its own distinct emotional character worth separating out clearly.
Why Funded Accounts Don't Simply Feel Like "Real" Live Trading
A funded account occupies a genuine middle ground between demo and fully personal live trading — the capital at risk is real in the sense that losing it has real consequences (losing funded status, program fees already paid), but it's not your own accumulated savings in the way a fully personal account represents. This middle-ground status can produce its own specific emotional pattern that doesn't map cleanly onto either the "demo doesn't feel real" dynamic or the "personal live trading feels maximally weighty" dynamic covered elsewhere in this series.
How This Shows Up in Practice
Some traders report that funded accounts feel closer to demo trading emotionally — genuine discipline gaps can persist longer than expected, since the capital, while consequential, doesn't carry the same direct personal financial weight as money drawn from one's own savings. Others report the opposite — the structured, rule-bound nature of funded programs (hard daily loss limits, explicit rules, an evaluation history already invested) creates its own distinct pressure that can feel more intense than personal trading in certain ways, even without the same raw personal-savings stake.
Why Understanding Your Own Specific Pattern Matters
Given that this dynamic genuinely varies between individual traders, the useful exercise isn't assuming a universal answer, but honestly tracking your own execution quality specifically across demo, funded, and personal live accounts if you trade across more than one of these contexts — the earlier journaling framework covered in this series applies well here, tagging trades by account type and reviewing whether execution quality genuinely differs meaningfully between them.
A Practical Response If You Find a Genuine Gap
If your own data shows a meaningful discipline gap specifically on funded accounts (in either direction — too loose or too cautious), treat closing that specific gap the same way you'd treat closing the demo-to-live gap covered earlier in this series — deliberate, gradual size or complexity adjustments specifically aimed at building consistent execution across whichever context currently shows weaker discipline, rather than assuming the gap will simply resolve itself with more time trading in that context without a specific, deliberate correction.
The Underlying Point
Funded accounts occupy a genuinely distinct psychological space between demo and fully personal trading, and the specific way that space affects any individual trader's discipline varies enough that it's worth tracking honestly in your own data rather than assuming a universal pattern — the goal, as with every account type covered throughout this series, is consistent execution regardless of whose capital, or which program's rules, happen to be governing a given account.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:35 pm
by Fairman
Why Chasing a Prop Firm Payout Changes Your Risk Behavior
Beyond the general funded-account psychology covered in the earlier post, the specific approach of a scheduled payout date on a funded account introduces its own distinct behavioral pattern worth understanding and guarding against directly.
Why Payout Timing Creates Unique Pressure
Most funded programs operate on defined payout cycles — reaching a certain date, or a minimum profitable period, before profits can actually be withdrawn. As a payout date approaches, there's a common and understandable pull to either protect existing gains more cautiously than the trading plan would otherwise call for, or, in the opposite direction, to push harder for additional gains specifically to maximize the upcoming payout amount — both of which represent a deviation from the consistent, rule-based execution this entire series has emphasized.
The Overly Cautious Version of This Pattern
As a payout date nears, some traders shift toward excessive caution — passing on genuinely valid setups specifically to avoid any risk to the current profitable position before the payout locks in, effectively trading a different, more conservative strategy than the one that actually built the profit being protected. This mirrors the performance-pressure caution covered in the earlier funded account post, but specifically triggered by payout timing rather than the funded status itself.
The Overly Aggressive Version of This Pattern
The opposite pattern involves pushing for additional gains specifically because a larger account balance at the payout date means a larger payout — taking looser, less disciplined setups or oversized positions in the days leading up to a payout date, driven by a desire to maximize that specific payment rather than by genuine setup quality. This is a distinct instance of the outcome-focused goal-setting problem covered earlier in this series, with the payout date functioning as a specific, recurring version of the monthly-target pressure already discussed.
Why Both Versions Undermine the Same Underlying Discipline
Both directions share the same root problem — allowing an external, calendar-based event (the payout date) to influence trade selection and sizing, rather than maintaining the same consistent criteria regardless of where that date happens to fall. A sound process doesn't need to know or care when a payout is scheduled; a process that does shift based on this timing has, in a meaningful sense, stopped being purely criteria-driven.
A Practical Safeguard
Treat payout dates purely as an administrative, financial event entirely separate from trading decisions — the same written plan and criteria should govern trade selection regardless of proximity to a scheduled payout, the same way the daily loss limit and confluence checklist covered throughout this series shouldn't flex based on any other external, non-market-related calendar consideration.
The Underlying Point
Payout timing is a genuine, specific, and recurring trigger for exactly the kind of discipline drift this series has repeatedly warned against — recognizing it as a distinct pattern, separate from ordinary trading pressure, is the first step toward maintaining consistent execution regardless of where a given trade falls relative to your account's payout cycle.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:37 pm
by Fairman
Treating a Trading Income as a Business Expense Line
For traders whose activity has grown into a genuine, meaningful income source, a specific mindset shift — treating trading costs the way an actual business treats its operating expenses — offers a useful, more disciplined framework than the more casual accounting most retail traders default to.
What This Framework Actually Involves
Rather than thinking of spread costs, platform fees, prop firm evaluation fees, and other trading-related expenses as vague, unquantified background costs, treating them explicitly as a business expense line — tracked, totaled, and weighed against gross trading income the same way any business tracks its cost of operation against its revenue — provides a considerably clearer, more honest picture of genuine net profitability than looking at raw gains alone.
Why This Matters Specifically Given Everything Covered Earlier in This Series
The spread and slippage costs covered earlier in this series, the position sizing math, the prop firm evaluation fees discussed more recently — all of these are genuine costs of doing business as a scalper, and a trader who doesn't track them explicitly as costs risks a distorted sense of actual profitability, overestimating genuine edge by focusing purely on gross gains without netting out the real expenses required to generate them.
A Practical Expense-Tracking Framework
Track, on a regular cadence (monthly is reasonable for most active scalpers), total spread and slippage costs incurred (estimable from your journal data, per the earlier journaling post), any platform or data subscription fees, prop firm evaluation costs if applicable, and any other genuine trading-related expenses. Compare this total explicitly against gross trading gains to arrive at a genuine net figure — the number that actually reflects whether the underlying activity is profitable once real costs are accounted for, not just the more flattering gross figure.
Why This Discipline Pays Off Beyond Simple Accounting Accuracy
Beyond the honest accounting value, treating trading this way tends to naturally reinforce several of the disciplines covered throughout this series — an explicit awareness of spread cost as a real, tracked expense reinforces the target-setting and session-selection discipline covered earlier; explicit tracking of evaluation fees reinforces more careful, deliberate consideration before committing to another prop firm attempt rather than treating repeated evaluation fees as a casual, unexamined cost.
Extending This to Tax and Formal Business Considerations
For traders whose activity has grown substantial enough to warrant it, treating trading with genuine business-level rigor may also extend to formal considerations — appropriate record-keeping for tax purposes, potentially formal business structuring depending on jurisdiction and scale — though the specifics of this vary considerably by location and are worth discussing with a qualified professional rather than relying on generic forum guidance for anything with genuine legal or tax consequence.
The Underlying Point
Treating trading costs with the same explicit, tracked rigor a genuine business applies to its expenses produces a more honest picture of actual profitability and reinforces several of the specific disciplines covered throughout this series — a natural extension of the "trading as business, not bet" mindset covered earlier, applied specifically to the financial accounting side of the activity.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:39 pm
by Fairman
When to Quit a Job to Trade Full-Time (And When Not To)
This is one of the more consequential decisions a developing trader faces, and it deserves a more careful, criteria-based approach than the excitement of an early good stretch typically produces on its own.
Why This Decision Gets Made Too Early So Often
A strong recent stretch — weeks or a couple of months of genuinely good results — tends to produce exactly the kind of borrowed, streak-driven confidence covered in the earlier post on the confidence trap, and this specific decision is one of the highest-stakes places that trap can manifest. The excitement of recent success, combined with the genuine appeal of trading full-time, creates real pressure to make this decision based on a small, recent, potentially unrepresentative sample rather than the kind of extended, tested track record that would actually justify it.
A More Reasonable Set of Criteria
A meaningful track record, not just a good recent stretch — ideally spanning multiple market conditions (trending, ranging, high and low volatility) and, critically, including at least one genuine losing stretch that was navigated according to your own stated process, not just a favorable run that hasn't yet been tested against real adversity.
Sufficient capital that position sizing doesn't need to be inflated beyond sound risk parameters to generate a livable income — a common, dangerous pattern involves undercapitalized traders taking oversized positions specifically to make full-time trading income "work" on too small an account, directly undermining the risk discipline covered throughout this entire series.
A financial cushion separate from trading capital — enough savings to cover a genuine, extended rough stretch without that stretch creating the kind of desperate, need-to-recover pressure that drives exactly the revenge trading and overtrading patterns covered earlier in this series. Trading to cover immediate, pressing living expenses with no cushion is a fundamentally different, more psychologically compromised position than trading with genuine financial breathing room.
Why "Never" Isn't the Right Answer Either
This isn't an argument against ever trading full-time — plenty of traders do transition successfully, and for some, the structure and focus of full-time trading genuinely improves their process compared to fitting it around other work. The argument is specifically against making this decision prematurely, based on a short, favorable, untested stretch, rather than a genuinely evaluated track record against the criteria above.
A Reasonable Middle-Ground Approach
Rather than a single binary decision, consider a gradual transition — reducing other work hours incrementally as trading income genuinely and consistently demonstrates itself over an extended period, rather than a single leap from full employment directly to full-time trading based on a recent hot streak. This gradual approach also provides natural checkpoints to honestly reassess before each further step, rather than committing fully based on an early, unrepresentative sample.
The Underlying Point
This decision deserves the same evidence-based, criteria-driven approach this entire series has applied to individual trades — a track record genuinely tested against adversity, adequate capital and cushion, and a gradual, checkpoint-based transition tend to produce considerably better outcomes than an excited leap made during an early favorable stretch that hasn't yet been tested against the inevitable difficult periods every trader eventually faces.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:40 pm
by Fairman
The Isolation of Full-Time Trading and How to Manage It
For traders who do successfully transition to full-time trading, a genuine, often underestimated challenge emerges that has nothing to do with strategy or discipline directly — the isolation of a work structure that, for many, lacks the built-in social contact of a traditional job.
Why This Isolation Is a Real, Distinct Problem
A traditional job, whatever its downsides, typically provides regular, structured social contact — colleagues, meetings, the simple presence of other people throughout a working day. Full-time trading, particularly for a scalper working from home during specific session hours, can eliminate most of this structured social contact entirely, replacing it with long, solitary stretches watching charts, which is a genuinely different daily experience than most other work arrangements provide.
How This Connects to Earlier Psychology Discussions in This Series
This isolation interacts directly with several patterns already covered — the identity-outside-of-results discussion becomes considerably harder to maintain when trading occupies not just your primary income source but also a large share of your daily social and structural context. The community discussion earlier in this series takes on added importance here too — for an isolated full-time trader, a trading community can become a more significant source of social connection than it would be for someone trading part-time alongside other work and its accompanying social structure.
Practical Approaches to Managing This
Deliberately schedule non-trading social contact, treating it as seriously as any other part of a sustainable trading routine — this isn't a luxury or a distraction from "real" trading work, it's a structural necessity that a traditional job would have provided automatically without requiring deliberate scheduling.
Consider working from locations with some ambient social contact — a coworking space, a coffee shop during appropriate hours — rather than exclusively from an isolated home setup, if isolation is genuinely affecting mood or trading performance.
Build structured activities into non-trading hours that provide genuine social contact and interests outside of markets, directly supporting the identity-outside-of-trading discussion covered earlier in this series, but with added urgency given how much of a full-time trader's day trading and markets can otherwise occupy.
Why This Deserves Direct, Serious Attention
Isolation's effects on mood and mental health are well-documented in general psychological research, and a trader experiencing meaningful isolation-driven mood decline is also, almost certainly, experiencing degraded trading performance as a direct consequence — connecting to the earlier post on sleep and physical health, isolation is another basic life-condition factor that genuinely affects trading execution quality, not a separate, unrelated lifestyle concern.
The Underlying Point
Full-time trading's isolation risk is a genuine, structural challenge specific to this particular work arrangement, not a personal failing or something to simply push through without addressing directly — building deliberate social structure into a full-time trading routine is as legitimate and necessary a part of sustainable practice as any of the more directly trading-focused disciplines covered throughout this series.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:42 pm
by Fairman
Diversifying Income So Trading Isn't Your Only Pressure Valve
Beyond the full-time-transition discussion covered in the earlier posts, there's a specific, related argument worth making directly: maintaining some income diversification, even after trading becomes a primary income source, offers genuine psychological protection that pure trading income cannot provide on its own.
Why Single-Source Income From Trading Specifically Compounds Pressure
When trading is genuinely the sole income source, every session carries not just the ordinary stakes of the trade itself, but the added weight of being the only mechanism currently covering living expenses — this compounds directly with several of the pressure-driven patterns covered throughout this series, since a losing stretch under these conditions isn't just a trading setback, it's a direct threat to financial stability with no other income cushioning the impact.
How This Differs From the Financial Cushion Discussion Already Covered
The earlier full-time-transition post recommended a savings cushion as one criterion for making the transition — this is related but distinct: even with an adequate cushion, having zero ongoing income diversification means that cushion is a depleting, one-directional resource during any rough trading stretch, rather than being supplemented by some other, independent income flow that continues regardless of how trading is currently performing.
What Genuine Diversification Might Look Like
This doesn't necessarily mean returning to full traditional employment — it can mean maintaining some part-time consulting or freelance work in a separate skill area, a small business venture, or other income streams that operate independently of trading performance and provide a genuine, ongoing counterbalance rather than a purely depleting reserve. The specific form matters less than the underlying function: some income that isn't contingent on how this week's or this month's trading actually goes.
The Psychological Mechanism This Actually Protects
Diversified income directly reduces the pressure that drives revenge trading, overtrading, and the outcome-obsessed goal-setting covered throughout this series — if a losing trading stretch doesn't threaten immediate financial survival because other income continues regardless, the psychological freedom to simply wait out a normal, expected variance-driven rough patch (per the earlier losing streaks post) without that patch itself creating additional pressure toward undisciplined recovery attempts is considerably easier to actually maintain.
Why This Isn't in Tension With Taking Trading Seriously
Maintaining some income diversification isn't a lack of commitment to trading as a serious pursuit — if anything, it protects the ability to trade well by removing exactly the kind of desperate, survival-driven pressure that most reliably degrades sound decision-making. A trader whose entire financial existence depends on this week's trading results is operating under a genuinely harder psychological condition than one with some independent income cushion, regardless of how skilled either trader actually is.
The Underlying Point
Income diversification functions as a direct psychological safeguard against several of the most damaging patterns covered throughout this series — not a hedge against trading's importance, but a structural protection that makes disciplined, patient trading considerably easier to sustain through the inevitable difficult stretches every trader eventually faces.
Re: Exponencial money management
Posted: Fri Sep 18, 2026 6:44 pm
by Fairman
Building a Support System Outside the Trading Community
The trading community discussion covered earlier in this series focused specifically on the benefits and risks of engaging with other traders. This post makes a related but distinct point: a support system entirely outside the trading world serves a genuinely different, complementary function that a trading-specific community, however well-chosen, cannot fully replace.
Why Trading-Specific Support Has Real Limits
Even a genuinely healthy trading community, of the kind described in the earlier post on that topic, is still organized around a shared, high-stakes financial pursuit — which means its members are simultaneously a support resource and, to some degree, participants in the same comparison and status dynamics covered in the earlier jealousy and comparison-trap posts. A support system entirely disconnected from trading doesn't carry this same built-in tension, offering a genuinely different kind of relational context.
What Non-Trading Support Actually Provides
People who care about your wellbeing independent of how your trading is performing offer a specific, distinct kind of grounding — connecting directly to the identity-outside-of-results discussion covered earlier in this series, relationships that don't have any stake in or awareness of your trading results provide a genuine anchor point that isn't affected by a losing streak, a missed setup, or any of the other trading-specific events that can otherwise dominate a trader's emotional landscape.
Why This Matters More for Full-Time or Heavily-Invested Traders
Connecting to the isolation discussion in the earlier post, traders whose daily structure revolves heavily around markets are at particular risk of their support system becoming entirely trading-centric by default, simply because trading occupies so much of their time and attention — deliberately maintaining relationships and activities entirely outside this world requires active effort precisely because it doesn't happen automatically the way it might for someone whose work naturally involves broader social contact.
Practical Ways to Build and Maintain This
Deliberately schedule time with people and in contexts that have nothing to do with trading, treating this with the same seriousness as any other part of a sustainable routine, similar to the scheduling recommendation in the isolation post. Resist the pull to make every conversation about trading, even with people who might be willing to listen — some genuine mental separation from the subject, in at least some of your relationships, supports the broader identity-diversification this series has emphasized throughout.
Why This Isn't in Conflict With Valuing Trading Community
This isn't an argument against the trading-specific community discussed earlier in this series — both serve genuinely different, complementary functions, and a trader benefits from having both a well-chosen trading community for the specific, trading-relevant support and learning it provides, and a broader support system entirely outside that world for the different, more unconditional grounding covered in this post.
The Underlying Point
A support system built entirely outside the trading world provides a distinct, non-substitutable form of grounding that even a genuinely healthy trading community cannot fully replace — worth maintaining deliberately, especially for traders whose daily structure otherwise revolves heavily around markets.